Showing posts with label first time home buyer. Show all posts

Monday, May 11, 2015

5 Things Not Necessarily Included in Your Home Purchase

The buyer of a historic Victorian home in upstate New York fell in love with the gigantic antique mirror in the foyer.  The mirror looked as if it were made for the space; it fit perfectly on the wall, & the frame matched the surrounding woodwork.  In fact, the mirror was so large, the buyer said she "couldn't imagine it going anywhere."

And yet, when she bought the house & went inside, the mirror was gone.  All that was left were some holes in the wall & the wallpaper behind it ripped & discolored where it was previously mounted.  The buyer promptly called her agent, who told her the mirror was personal property & didn't transfer with the house.

This scenario plays out in some form or another all the time.  In real estate transactions, there are gray areas when it comes to personal property.  Some contracts spell out exactly what's to be left behind for the new owner, while others are vague.

Don't assume anything you see on the property comes with the house.  If you intend to buy a home & there's something in particular you want, speak, up early.  Put your request in writing so that nobody is disappointed when the deal closes.

Here are five things that are often overlooked or not covered in a real estate transaction & that can lead to a dispute.

1.  Appliances

There are norms & customs in every market, which is why it's important to work with a local real estate agent who knows the ins & outs.  And surprisingly, it's not the norm everywhere to include all major household appliances, such as a refrigerator or dishwasher, with the property.  Worse, even if appliances are included, they might not be what you bargained for.

For example, a buyer was purchasing a home with top-of-the-line kitchen appliances.  In the property's marketing brochure, the real estate agent had highlighted the high-end stainless steel appliances.  Even though the contract stated that "appliances included in sale," however, the buyers were shocked when they discovered, upon taking ownership, that the seller had replaced the high-end stainless steel appliances with low-end models.  This led to arbitration, & the seller had to return the appliances.

The lesson learned:  Find out when making your offer if including appliances is customary in your market.  If there's any doubt, be sure to put it in writing - & be specific.  Make sure that "existing" appliances are included, or even go as far as to spell out the specific appliances, such as Bosch Dishwasher & Wolf Range.

2.  Window Coverings

Window coverings are another issue that often results in some nasty e-mail exchanges after a sale.

In nearly every market, the custom is that if there are window coverings present, they stay with the new owner.  Sometimes, there are shades & there are drapes.  The shades may be fully fitted for the window & attached.  But the drapes may be decorative.  Sometimes the seller, w ho had the drapes custom made to match the furniture, will want to exclude the drapes from the sale.  If you don't see it written anywhere or haven't heard about it, get the inclusion of window coverings in writing.  Along with the appliances, specify that you want the "existing window coverings."

3.  Personal Property

As with the drapes or the gigantic mirror noted above, the seller may have a specialty light fixture or a piece of art that appears designed to fit that space.  Or there may be furniture that fits so perfectly into a room, nobody could imagine anything else going there.   Here again, these items are personal property, & the seller may have no intention of letting them go, no matter how obvious it seems to the buyer than they should stay.  Always assume that any personal property, much like the beds & furniture, will not transfer to the new owner.

4.  Flat Screen TVs & Mounting Materials

Often, a seller may have had a high-def, flat-screen TV professionally mounted above the fireplace or on the wall like a piece of art, with the wires running through the walls.  As a result, TVs - long considered personal property - are showing up more & more in real estate negotiations.  But given a history of TVs as personal property, buyers shouldn't assume that a flat-screen TV, its wires or mounting brackets would stay behind after the sale.
5.  Kitchen or Bath Hardware

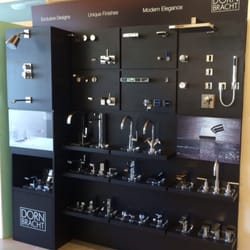
Hardware - in the form of doorknobs, kitchen cabinet pulls, bed & bath fixtures, & so on - should always transfer to the new owner.  This is just common sense.  These items are permanently attached to & therefore should stay with the property.  In fact, it used to be understood that "anything attached to the property stays with the property."  During the foreclosure drama, however, it wasn't uncommon for the seller to remove nearly all fixtures & finishes from home before it was foreclosed on.  This was their last chance to salvage some part of the house or even make a quick buck selling these items on the side.  If you're considering buying a home in foreclosure, just be aware that it is sold "as-is," meaning how you see the home.

Items to be Sold Separately

Sometimes sellers will decide that they want to keep something, or that they aren't interested in parting with it for free.  What is common is for the buyer to separately make an offer to purchase some of the seller's stuff.
Advice to Sellers

If you plan to take something with you, document it in all of the marketing materials (both print & online) so that there's no doubt in the buyer's mind what stays & what goes.  When a buyer makes an offer, they can factor any exclusion of property into their price.

 
Advice to Buyers

Be as detailed as possible from the beginning.  If there's something in particular you like & want to be sure stays, ask the listing agent during the open house.  If they tell you yes, get it in writing.


Shared from:  http://www.zillow.com/blog/5-things-not-necessarily-included-in-your-home-purchase-86738/

Getting Married? Skip the Fancy Plates and Ask for a Down Payment Instead!


They already have the high-powered blender, the 800-thread-count sheets, and the stemless wineglasses. And while they could always register for even more kitchen gadgetry and overstuffed throw pillows, some modern couples have their eyes on a different kind of wedding gift. What many of them want more than anything else is a house—or, more specifically (and reasonably), the down payment that will unlock the front door.
A growing number of altar-bound lovebirds are rethinking the traditional retail-based wedding registry (or registries, in many cases). Some are nudging their wedding guests toward online crowdfunding-style registries, designed to accept contributions to a couple’s down payment goals. Others are quietly suggesting “money for the house” when asked about their preferred present. Either way, plenty of couples are reconsidering altogether this gift-receiving opportunity in light of what they truly need.
A range of factors is at play here, the most obvious of which is the higher average marrying age—27 and 29 for women and men, respectively—than in past generations. It’s hardly a secret that many 20- and 30-somethings are temporarily sidestepping marriage while they establish careers, travel the world, hit up trivia night guilt-free, and, well, search for the right someone to marry.
Then again, even some younger couples seem to think that receiving a mountain of swanky home accessories before owning a home is putting the cart before the horse. After all, you can’t feather a nest if you don’t have a nest to begin with.
Twenty-five-year-old Daniel Barros and his fiancĂ©e, Traci Whiting, 24, of Plano, TX, are getting married in October. When they started thinking about setting up a gift registry, they were struck by the reality of their living situation.
“We live in an 800-square-foot apartment,” Barros said. “Even if we wanted a bunch of wedding presents, we wouldn’t have anywhere to put them. Getting that down payment together is our top priority, and we’re grateful for any amount our friends and family are willing to give to make that happen.”
To help achieve their goal of $5,500, Barros and Whiting set up a registry atFeatherTheNest.com, a Florida-based crowdfunding site that allows “nesters” to register for anything from contributions toward a down payment to funds for home improvement projects. Beth Butler, principal at the site, says crowdfunded registries offer couples a way to involve their friends and family in the most important purchase they’ll ever make.
“When you’re choosing a gift from a traditional retail registry, you’re pretty much bound to the prices of the items the couple has chosen, and even then, you’re likely giving them something they may forget about at some point in their marriage,” Butler said. “But helping a couple get into their first home, that’s a contribution they won’t ever forget.”
Butler said that her site, which launched in May 2014, now sees 15 to 20 “nests” (as each fund is called) per month.
Other similarly functioning sites—such as HatchMyHouse.com andDownPaymentDreams.com—offer comparable services, typically for the cost of a small percentage of the couple’s gift total.
Rieve MacEwen, president and co-founder of Hatch My House, estimates that the monetary value of the average U.S. wedding registry hovers between $8,000 and $8,500—an amount that, if applied to a down payment (generally at least 20% of a home’s price), could certainly give a significant boost to a couple’s savings efforts.
But not everyone is so enthusiastic. Teresa Krebs, who started Down Payment Dreams in 2009 and has since hosted some 800 registries, said that a handful of users have reported a lukewarm response from family members, some of whom felt that asking for money was tacky. But, as Krebs points out, “a registry is just a suggestion, and a down payment registry is no different. It’s a couple’s way of saying, ‘We’d like your presence at the wedding, and if you choose to bring a gift, this is what would be most helpful to us.’”
Just how helpful? When Sally and Yann Sauvignon married in 2010, they set up a registry at Hatch My House, along with two traditional retail registries. About a year after their 200-guest wedding, the couple was able to use their down payment gifts to cover the closing costs on their new home in the San Francisco Bay Area.
“We weren’t quite sure how it would be received, but I think about a third of our gifts were given through the Hatch My House site,” Sally Sauvignon said. “It was a really neat way to connect our friends and families to a goal that was really important to us.”
To be sure, the concept of a down payment as a wedding gift is still a bit of an outlier. The majority of engaged couples are still filling their conventional registries with flatware and “good” china. But MacEwen—who says Hatch My House has hosted roughly 2,600 registries since its founding in 2009—is confident that the next decade will see a more pronounced shift in the wedding gift tradition altogether.
“What will really change the way people use gift registries is when they look beyond the idea of purchasing an item, and decide they want to be a part of someone’s overall life experience instead,” MacEwen said. “Buying a home and getting married are two of life’s biggest events. Over time, I think people will realize that it makes a lot of sense to connect the two.”

How to crowdfund your dream home

Don’t be sheepish. Wedding registries of any variety are simply a series of gift ideas for wedding guests who are already planning to buy a present. A down payment registry is no different—it’s just a suggestion.
Spread the word. Share the specifics of your down payment registry on your wedding website, on any wedding shower invitations, and when friends and family ask where you’re registered.
Be grateful. In addition to the thank-you notes that you’ll send promptly after the wedding, consider sharing periodic updates about your home-buying adventures with the people who helped make it possible. It’s just another way to show your gratitude.
Leave a paper trail. When applying for a home loan, you’ll need to verify that your down payment is yours, free and clear, and not the result of another loan. Most down payment crowdfunding sites will  document the nature of the monetary gift.


Shared from:  http://www.realtor.com/advice/down-payment-wedding-registry/

Friday, March 6, 2015

10-Step Guide to Buying a House

guides_nmbr_1Are You Ready to Become a Homeowner?
Whether you’re becoming a homeowner for the first time or you’re a repeat buyer, buying a house is a financial and emotional decision that requires the experience and support of a team of reliable professionals


guides_nmbr_2Get a REALTOR®
In the maze of forms, financing, inspections, marketing, pricing and negotiating, it makes sense to work with professionals who know the community and much more. Those professionals are the local REALTORS® who serve your area.Read more »

guides_nmbr_3Get a Mortgage Pre-approval
Most first-time buyers need to finance their home purchase, and a consultation with a mortgage lender is a crucial step in the process. Find out how much you can afford before you begin your home search. Read more »


guides_nmbr_4Look at Homes
A quick search on realtor.com® will bring up thousands of homes for sale.  Educating yourself on your local market and working with an experienced REALTOR® can help you narrow your priorities and make an informed decision about which home to choose. Read more »

guides_nmbr_5Choose a Home
While no one can know for sure what will happen to housing values, if you choose to buy a home that meets your needs and priorities, you’ll be happy living in it for years to come. Read more »


guides_nmbr_6Get Funding
The cost of financing your home purchase is usually greater than the price of the home itself (after interest, closing costs and taxes are added). Get as much information as possible regarding your mortgage options and other costs. Read more »

guides_nmbr_7Make an Offer
While much attention is paid to the asking price of a home, a proposal to buy includes both the price and terms. In some cases, terms can represent thousands of dollars in additional value – or additional costs – for buyers. Read more »


guides_nmbr_8Get Insurance
No sensible car owner would drive without insurance, so it figures that no homeowner should be without insurance, either. Real estate insurance protects owners in the event of catastrophe. If something goes wrong, insurance can be the bargain of a lifetime. Read more »

guides_nmbr_9Closing
The closing process, which in different parts of the country is also known as “settlement” or “escrow”, is increasingly computerized and automated. In practice, closings bring together a variety of parties who are part of the real estate transaction. Read more »


You’ve done it. You’ve looked at properties, made an offer, obtained financing and gone to closing. The home is yours. 


Reposted from:  http://www.realtor.com/advice/10-step-guide-to-buying-a-house/?iid=rdc_advice_article_editors-picks

Thursday, January 8, 2015

Our website!


Our website, www.maryandbengriffith.com has been spiffed up & reflects our brokerage change last year.  It is chock full of information about the new group we're with.  Please take a look & don't hesitate to get in contact with us if we can be of service.  We can be reached at (727) 804-4468.